Labor Day will be here soon! Our office will be closed in observance of this holiday on Sept. 7th. We will be open again on Tuesday, the 8th!
Stay safe and have a wonderful long weekend! 💙
Labor Day will be here soon! Our office will be closed in observance of this holiday on Sept. 7th. We will be open again on Tuesday, the 8th!
Stay safe and have a wonderful long weekend! 💙
Wildfire Update – 2026
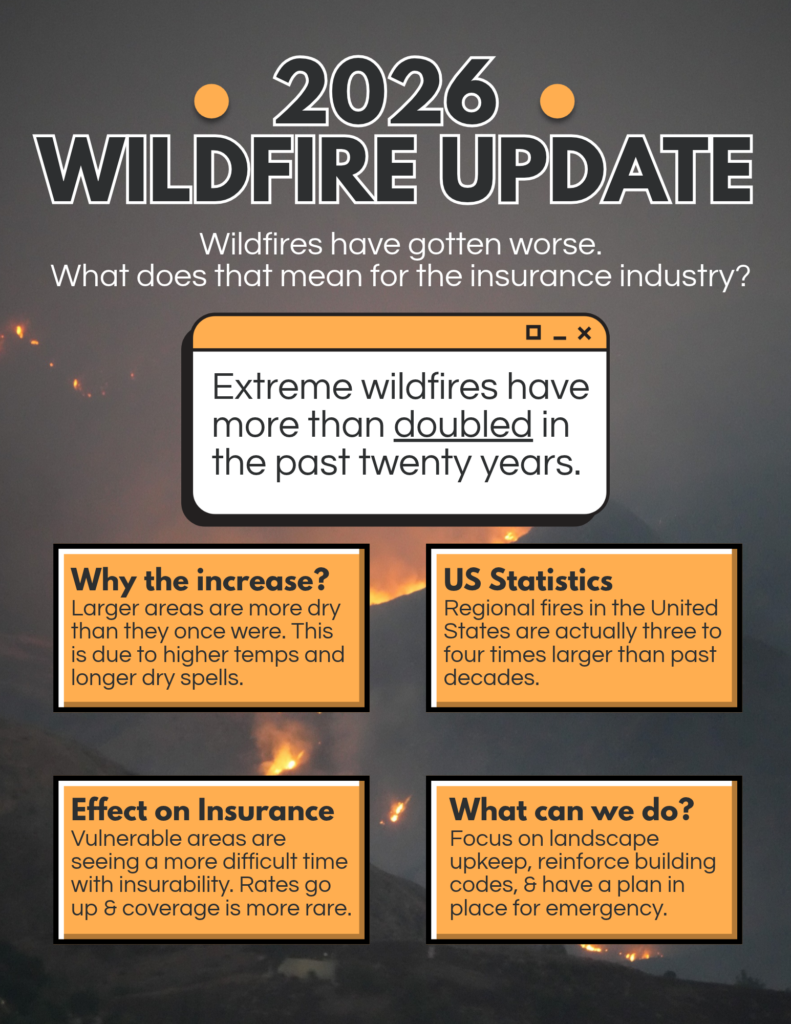
Extreme Wildfires have increased by over double in the past twenty years.
Why have they increased? The world is warmer and more dry in general than it was twenty years ago. This has caused dry spells to last longer, increasing the area of wildfires along with their duration. Climate change including warmer Spring and Summer seasons dries out the soil faster. Autumns have also been more dry, which extends the window of fire risk.
In the US, some regions are seeing an uptick in wildfire activity that is three to four times larger than it was. US forest tree cover is burning twice as much as it has in the past due to fires ravaging them.
What does this mean for insurance? Simply put, it’s harder to obtain insurance in areas affected by these fires. Many carriers recognize that they cannot sustain large losses caused by wildfire areas, causing them to pull out of a region whose fire score is too high. This means that individuals living in areas with high Protection Classes (or fire scores) have a tough time finding coverage. For those that can find coverage, their premiums are often higher to offset the risk of insuring a property in a high fire-risk zone.
Is there anything that my community can do? Yes. Several steps can be taken to reduce the risk of extensive damage caused by wildfire.
Concerned about fire? Give us a call! We are happy to review your policy to ensure that you have adequate coverage in the event of a fire. Some of our carriers even have measures in place for wildfire mitigation if your home is in a high fire-risk zone.
August 26th is Women’s Equality Day! 💗
As a woman-owned business, the sacrifices of the women that came before us to grant us this opportunity are so important to us.
Our liberties are not guaranteed, we all need to continue to support equality where we can.
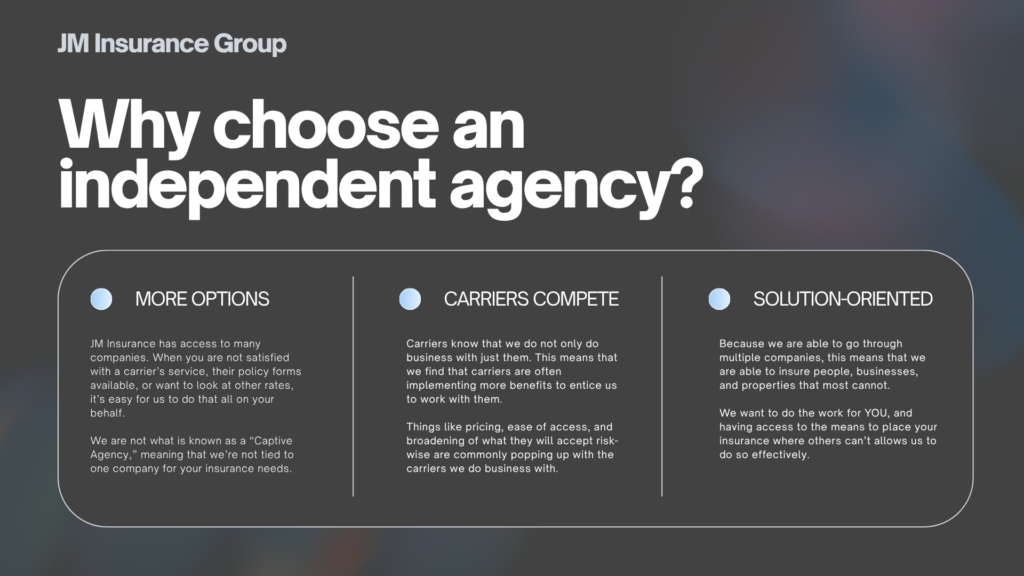
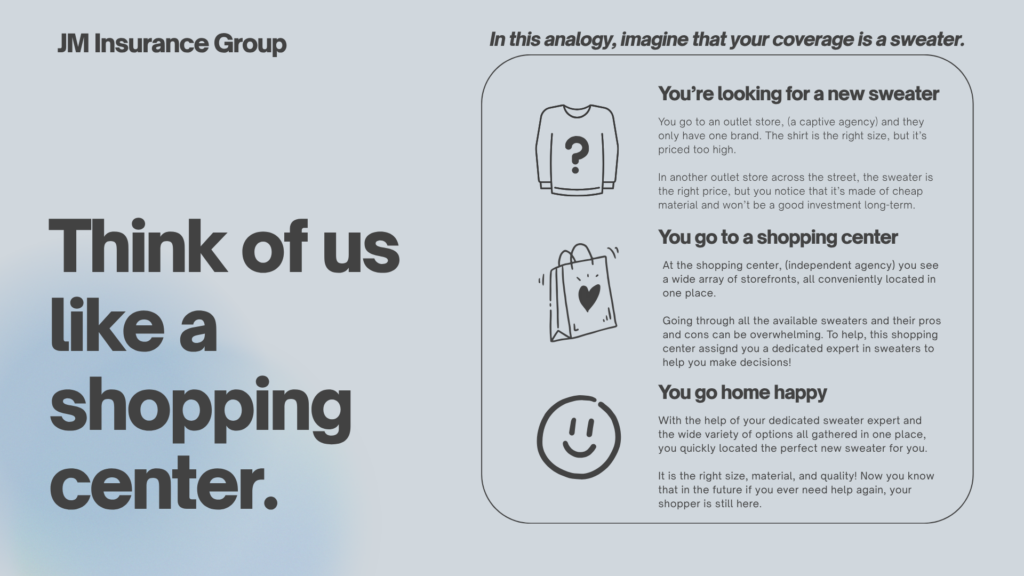
“What the heck does this mean on my policy?”
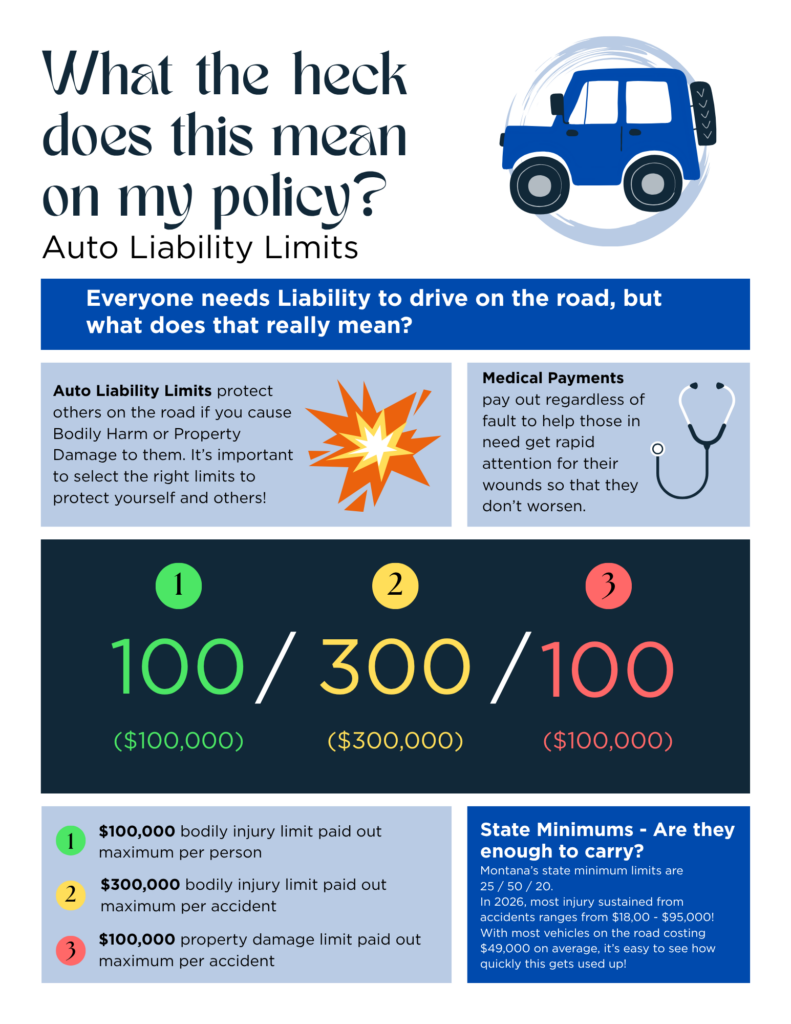
Time to talk Auto Liability Limits! What are they? How are they normally listed on your policy? How much is enough? Everyone needs Liability to legally drive on the road, but what does that really mean?

Auto Liability Limits protect others on the road if you cause Bodily Harm or Property Damage to them. It’s important to select the right limits to protect yourself and others!
Medical Payments pay out regardless of fault to help those in need get rapid attention for their wounds so that they don’t worsen.
** What does it mean when your policy says “100 / 300 / 100”? **
– The first number is in thousands. For example, 100 = $100,000. This is the amount that you have available for Bodily Injury damage to another person in an accident.
– The second number is in thousands. For example, 300 = $300,000. This is the amount that you have available for Bodily Injury damage to other people in the WHOLE accident.
– The third number is also in thousands. For example, 100 = $100,000. This is the total amount per accident you have available for all Property Damage you cause to a third party.
Keeping this information in mind, are State Minimums in MT enough to protect you and others on the road? Likely not. Montana’s state minimum requirements only state you need “25 / 50 / 20.” This means only $25,000 per person Bodily Injury, $50,000 per Accident Bodily Injury, and $20,000 per accident Property Damage.
With most auto accident-related hospital visits ranging from $18,000 – $95,000, there is quite the margin of risk for hurting others on the road with these limits. Also, with most new vehicles costing twice as much as the state minimum requirement for Property Damage, you are exposing yourself to a lot of potential issues financially.
What can people do if you cause more damage than what your insurance will cover? They can pursue litigation against you, and ask that you pay out of pocket for the damages not covered by your insurance. This can result in them targeting your personal assets or even garnishing your wages!
What steps can you take to prevent mold growth in your home? 🦠
Avoid keeping spaces stuffy! Run fans while using the shower or kitchen, and open windows to provide a breeze.
Keep an eye on plumbing, roofs, and gutters often. If you have a leak, take steps to prevent water from pooling/fix the damage as best as you can within the first 48 hours to have the best chance of avoiding microbial growth.
Keep air flowing! Don’t place furniture directly against walls.
If you have a humid area of your home, use a de-humidifier. Try to keep rooms at a humidity level of 30-60%.
Do not install wall-to-wall carpet in moisture-rich areas.
Open your windows often, but NOT when it is humid outside!
Do you have a high wind/hail deductible on your home policy? We have options! 💨
There are plans called Deductible Buyback plans that pay an amount towards your deductible. These plans usually come at a yearly cost, and can help lessen the financial strain on your wallet when it comes to the out of pocket expense tied to filing a claim.
Call us today at 406-534-8008 to learn more!
Remembering and honoring those who made the ultimate sacrifice for our country. Our office will be closed in observance of Memorial Day. 💙
#MemorialDay
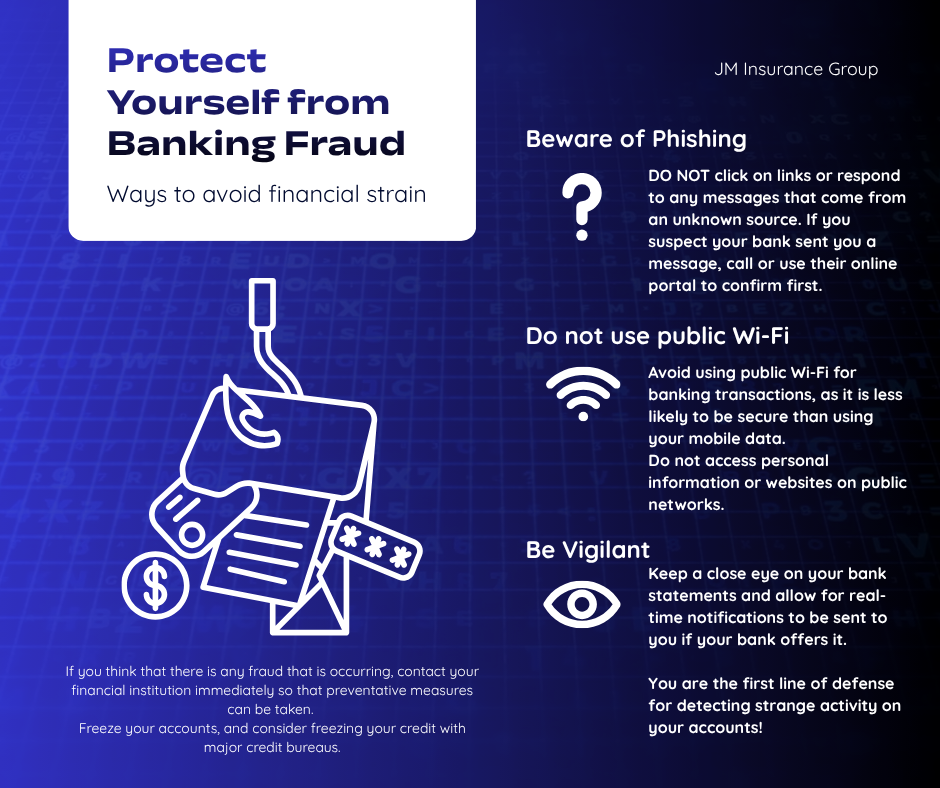
Stay alert, prevent banking fraud before it happens!
**Beware of Phishing**
DO NOT click on links or respond to any messages that come from an unknown source. If you suspect your bank sent you a message, call or use their online portal to confirm first.
**Do not use public Wi-Fi**
Avoid using public Wi-Fi for banking transactions, as it is less likely to be secure than using your mobile data.
Do not access personal information or websites on public networks.
**Be Vigilant**
Keep a close eye on your bank statements and allow for real-time notifications to be sent to you if your bank offers it.
__________________________________________
If you think that there is any fraud that is occurring, contact your financial institution immediately so that preventative measures can be taken.
Freeze your accounts, and consider freezing your credit with major credit bureaus.